
Start Your Arborist Report Insurance Claim With Evidence
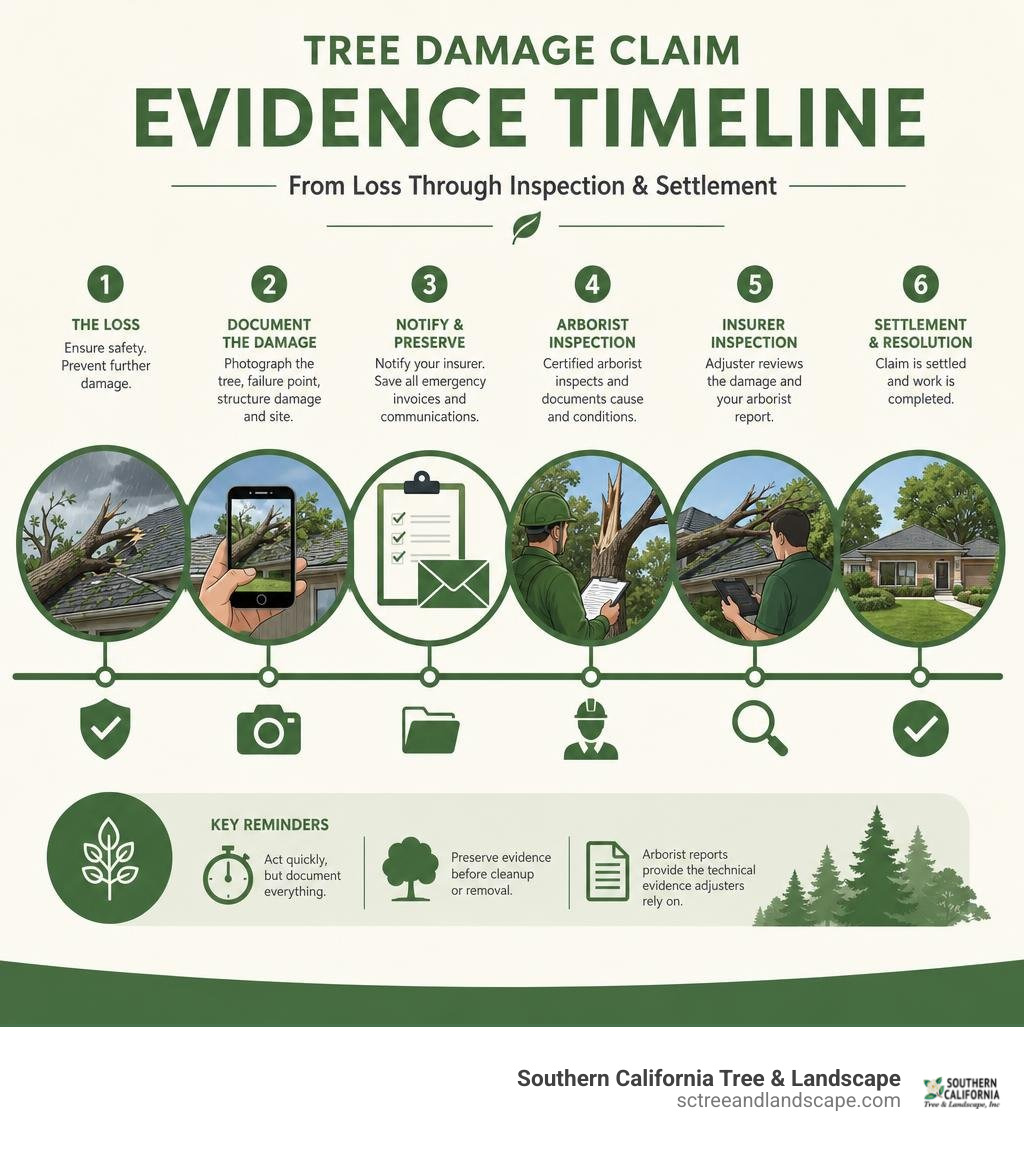
A strong arborist report insurance claim starts before the tree is cut up or hauled away. First, protect people and prevent further damage. Then photograph the tree, its failure point, the roof or structure damage, and the surrounding site. Notify your insurer, save every emergency invoice, and hire a certified arborist to document whether storm force, root failure, or decay caused the loss.
That report gives the adjuster technical evidence a basic tree-removal quote cannot provide. It can show whether the failure was sudden and storm-driven rather than the result of a known, neglected hazard – a key issue when coverage is disputed.
For HOA managers and Southern California property owners, speed matters. Preserve the evidence, but do not delay urgent mitigation such as tarping a damaged roof or securing dangerous hanging limbs. Most policies treat a tree that damages a covered structure very differently from one that falls harmlessly in an open yard, and debris-removal limits may apply.
I am Troy Basmajian, President of Southern California Tree & Landscape, and I lead teams that manage tree care, emergency response, and property protection for residential, commercial, HOA, and municipal clients throughout Southern California. My experience with arborist report insurance claim documentation helps property managers and owners understand what to preserve, what to request, and how to move a tree-damage claim forward.
Arborist report insurance claim glossary:
Understanding the Arborist Report Insurance Claim Process
When a tree crushes a garage or drops a massive limb through a tile roof, the resulting financial fallout can be dizzying. Across the insurance industry, estimates show that approximately 10% to 15% of homeowner property claims face an initial denial or significant underpayment. In many tree-related claims, the sticking point comes down to causation: did a covered weather peril cause the failure, or was the loss the result of unaddressed homeowner neglect?
To bridge this gap, policyholders need defensible causation evidence. Standard claims adjusters evaluate dozens of diverse property losses each week, from burst plumbing pipes to kitchen fires. They simply do not have the specialized arboricultural background required to evaluate biological growth rates, internal tree rot, or wood shear mechanics. Relying on an expert storm damage tree service gives you the technical backing required to substantiate policy language and prove that a loss was sudden, accidental, and covered under your policy terms.
Why Insurers Require an Arborist Report for Tree Damage Claims
Insurance policies are legal contracts built around specific perils and strict exclusions. In property damage claims involving fallen trees, the legal burden of proof rests on demonstrating that a covered peril—such as severe gale-force wind, heavy microbursts, or lightning—served as the primary trigger for the structural impact.
Loss adjusters operate under a standard of foreseeability. If an adjuster inspects a fallen tree and spots mushrooms sprouting near the base or a hollow cavity in the trunk, their initial instinct is often to categorize the collapse as preventable wear-and-tear or long-term neglect. A general contractor’s estimate only provides repair pricing; it cannot scientifically explain why the tree fell. Certified arborist assessments supply the formal botanical, structural, and mechanical evidence loss adjusters require to validate that the event was sudden and unforeseeable.
Key Elements Included in an Arborist Report Insurance Claim Document
A comprehensive arborist report serves as a legal and forensic document. To withstand carrier scrutiny and substantiate an arborist report insurance claim, it must contain specific technical data:
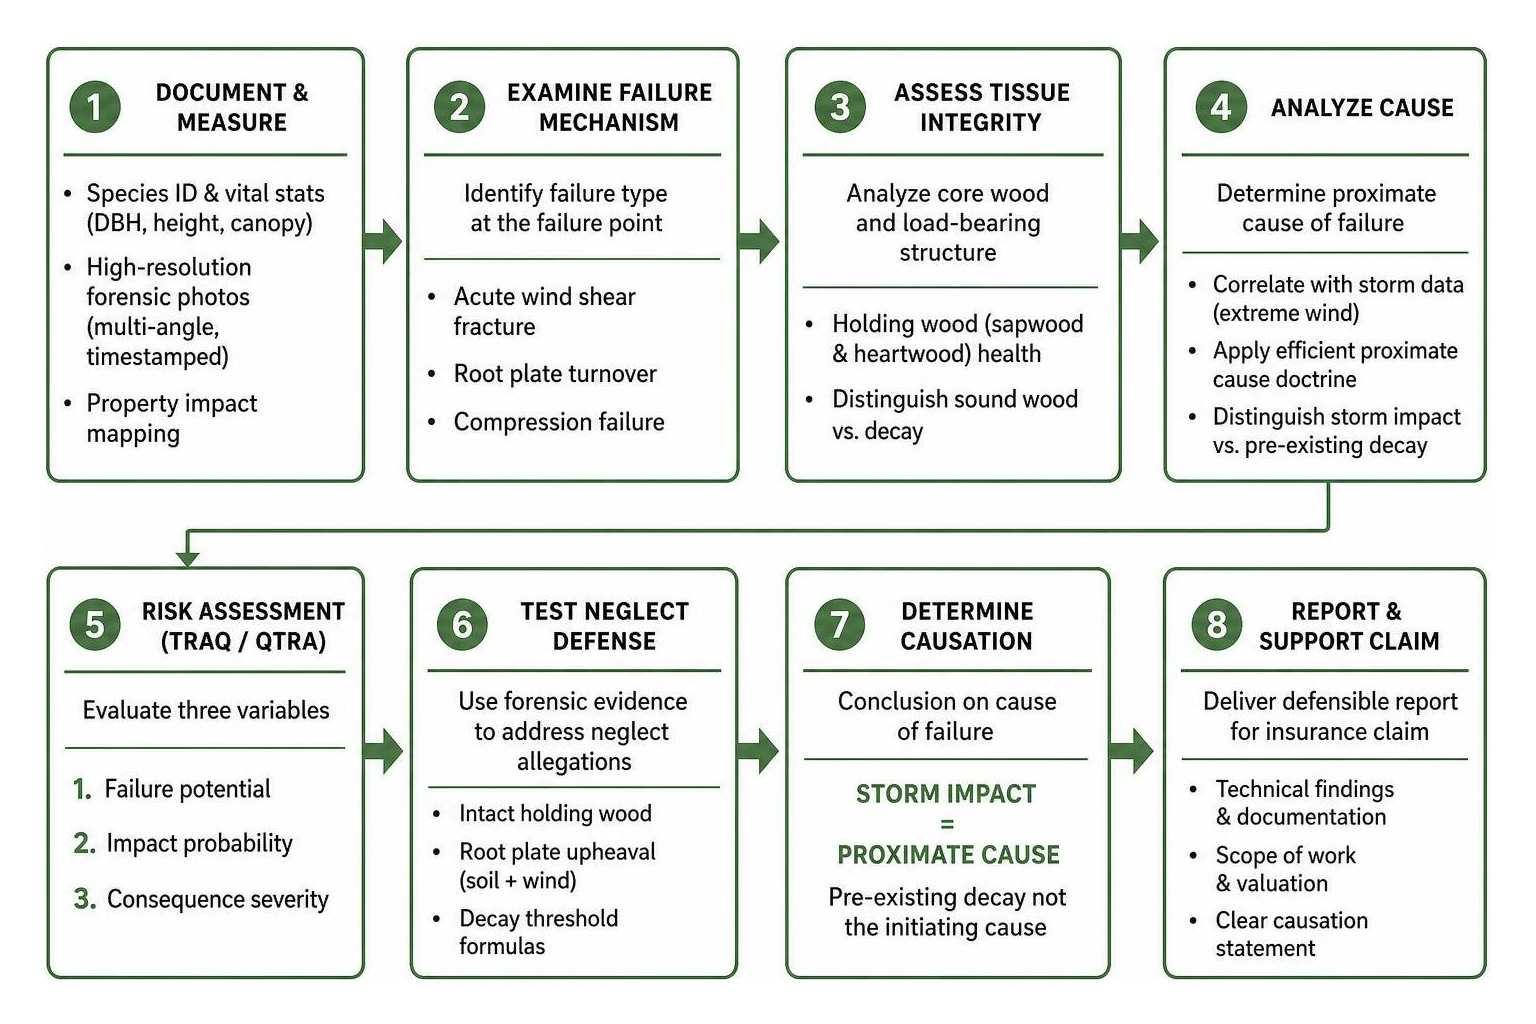
- Species Identification and Vital Stats: Precise botanical and common naming, trunk diameter at breast height (DBH), canopy spread, and height.
- Biomechanical Failure Analysis: An examination of the failure point, distinguishing between acute wind shear fracture, root plate turnover, or compression failure.
- Core Wood and Tissue Integrity: Physical documentation of whether the structural load-bearing sapwood and heartwood were healthy and functional prior to the failure.
- High-Resolution Forensic Photography: Timestamped, multi-angle images detailing the root flare, trunk cross-sections, foliage health, and property impact points.
- Fair Market Scope and Valuation: Defensible itemization of debris extraction, crane requirements, hauling logistics, and tree replacement valuations.
Proving Causation: Storm Impact vs. Pre-Existing Tree Decay

When an insurer attempts to deny a claim based on the “pre-existing disease” defense, our certified arborists perform a forensic cross-section analysis. Adjusters frequently confuse cosmetic canopy dieback or superficial bark decay with terminal structural failure.
In forensic arboriculture, the presence of surface bracket fungus does not automatically mean a tree was structurally unstable. If the outer rings of load-bearing wood (the holding wood) were biologically sound and intact, the tree possessed sufficient structural integrity under normal conditions. Acute mechanical stress from sudden wind gusts—often confirmed by National Weather Service local radar logs—is what caused the lateral shear failure. Under the insurance doctrine of efficient proximate cause, if a covered peril (such as extreme wind) set the chain of events in motion, coverage should apply even if minor, non-critical decay was present.
Standardized Risk Methodologies: TRAQ and QTRA Failure Analysis
To eliminate subjective guesswork, consulting arborists rely on standardized diagnostic frameworks such as TRAQ (Tree Risk Assessment Qualification) and QTRA (Quantified Tree Risk Assessment). These methods evaluate three distinct variables:
- Failure Potential: The mechanical likelihood of a specific tree part snapping or uprooting.
- Impact Probability: The likelihood of the failing part striking a designated target (like a house, fence, or patio).
- Consequence Severity: The potential monetary and structural damage resulting from the impact.
Applying these recognized frameworks provides objective credibility. Insurers and public adjusters respect assessments conducted by qualified certified arborists because the findings are grounded in biomechanical science rather than casual visual estimates.
Overcoming the Neglect Defense with Forensic Evidence
Carriers frequently deny coverage by asserting that the policyholder failed to maintain their property. We dismantle this neglect argument using physical, verifiable metrics:
- Intact Holding Wood: Demonstrating that bright, uncompromised wood fibers snapped under sudden torsion forces rather than crumbling from brown or white rot decay.
- Root Plate Upheaval: Proving that saturated soils combined with high lateral wind loads levered healthy root systems out of the earth, as opposed to self-contained root rot failure.
- Decay Threshold Formulas: Calculating the residual wall thickness to confirm the tree was well above standard hazard failure thresholds before the storm.
- Historical Maintenance Records: Incorporating past pruning, pest treatments, and safety evaluations to show proactive property management.
What Homeowners Insurance Policies Actually Cover After Tree Damage
Navigating insurance coverage requires understanding how policies distinguish between structural impacts and open-yard debris.
| Damage Scenario | Standard Policy Coverage Type | Typical Reimbursement Rules & Limits | Arborist Evidence Needed |
|---|---|---|---|
| Tree Falls on House or Attached Garage | Dwelling Coverage (Coverage A) | Full repair cost of structure minus deductible; tree removal from structure covered. | Biomechanical failure report proving wind/storm causation. |
| Tree Falls on Detached Garage, Shed, or Fence | Other Structures (Coverage B) | Typically capped at 10% of total Dwelling Coverage limit. | Structural impact photos and itemized removal scope. |
| Tree Falls on Open Lawn/Driveway (No Damage to Built Structures) | Debris Removal Additional Coverage | Heavily restricted; usually only covers removal if blocking a driveway or handicap ramp. | Documentation of access blockage or municipal hazard. |
| Neighbor’s Tree Falls onto Your Property/Structure | Your Own Policy (Coverage A or B) | Handled by your insurer unless neighbor had prior written notice of an active hazard. | Historical notice records, species identification, hazard timeline. |
| Standing Tree Damaged but Has Not Yet Fallen | Excluded / Routine Maintenance | Generally $0 unless proven to be in an imminent state of collapse onto a covered structure. | TRAQ imminent hazard assessment and structural target risk analysis. |
Structural Damage vs. Fallen Trees on Open Property
The single most frustrating discovery for many homeowners is that standard insurance policies protect structures, not yards. If an eighty-foot pine falls neatly across your lawn without touching a building, fence, or driveway, standard policies rarely pay for removal. The policy views this as routine landscaping maintenance.
However, when a tree impacts a covered structure, the insurer is responsible for the cost of crane operations, stabilization, and debris extraction required to safely remove the weight from the building. Understanding local municipal tree ordinances and structural coverage distinctions is crucial to filing properly.
Policy Limits for Tree Debris Removal and Landscaping Caps
Even when coverage applies, distinct sub-limits come into play:
- Debris Removal Limits: Most policies cap debris removal at $500 to $1,000 per tree. Because professional removal of a large fallen tree typically ranges from $500 to $2,500+ depending on size and technical complexity, standard debris limits can leave homeowners with out-of-pocket balances if not correctly allocated under structural extraction.
- Landscaping Coverage Caps: Landscaping replacement is usually capped at 5% of the dwelling’s insured value, with per-tree limits (often $500 to $1,000 per specimen).
- Proactive Tree Removal Exclusions: Insurers almost never pay to take down a standing tree simply because it is diseased. Taking action before disaster strikes remains the owner’s responsibility, though our essential tree care guide outlines how regular maintenance keeps your property safe and compliant.
How to File and Dispute an Arborist Report Insurance Claim
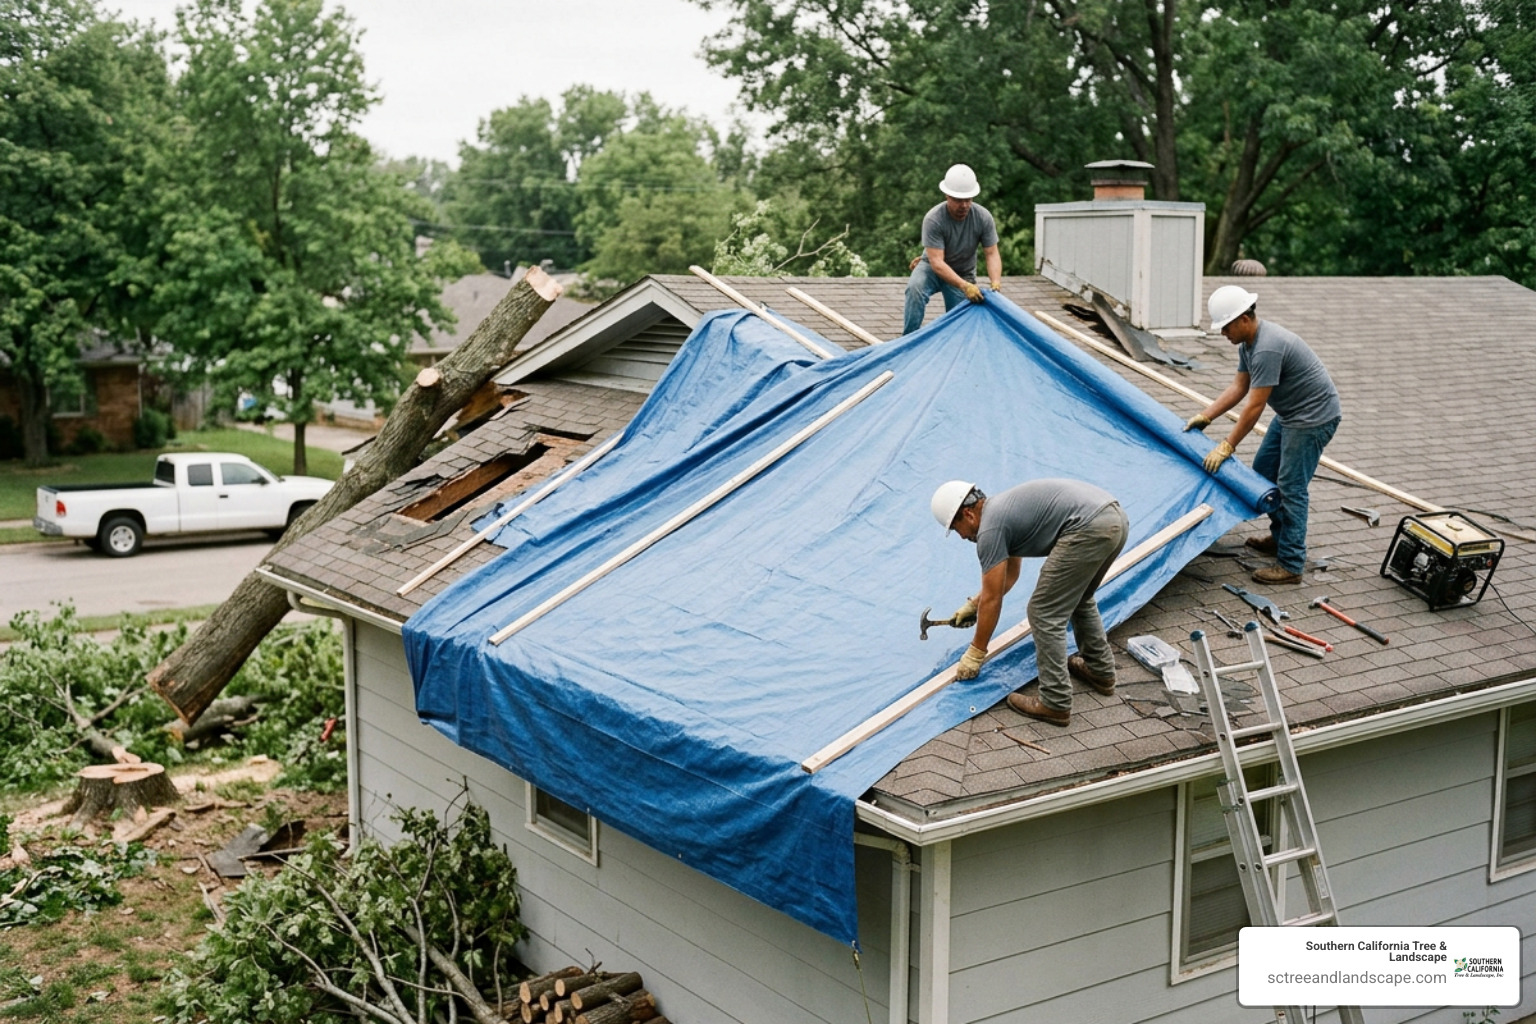
Filing a successful claim requires quick, organized action. Policyholders have an explicit “duty to mitigate,” meaning you must take reasonable steps to prevent secondary damage—such as water intrusion or mold growth—immediately after an incident.
If your initial claim is delayed or challenged, understanding how insurance claim documentation operates can help you supply the precise details adjusters need. When an emergency strikes at night, working with an experienced 24 hour emergency tree removal team ensures your home is stabilized while preserving critical evidentiary material for your adjuster.
Step-by-Step Strategy to Submit an Arborist Report Insurance Claim
Follow this structured process to build an airtight claim package:
- Ensure Site Safety: Check for downed electrical lines, unstable hanging branches, and structural shifts before approaching the site.
- Preserve the Evidence: Before calling a crew to chip or haul away the wood, take dozens of wide-angle and macro photos of the root base, trunk break point, and all structural contact points.
- Execute Emergency Mitigation: Install tarps, shore up damaged framing, and hire a professional emergency tree removal company to stabilize the structure.
- Obtain Official Weather Data: Gather local storm logs, barometric readings, and peak wind gust reports from the National Weather Service for your specific date of loss.
- Commission a Certified Arborist Report: Have an ISA-certified arborist perform a comprehensive diagnostic inspection and generate an insurance-grade assessment.
- Submit an Itemized Claim Package: Deliver the arborist report, emergency mitigation invoices, weather records, and contractor estimates directly to your adjuster as a unified package.
Challenging Denials with Public Adjusters and Policy Appraisals
If your carrier issues a denial letter citing pre-existing decay or lack of maintenance, do not accept it as the final word. Homeowners across the country have successfully overturned denials by mounting evidence-based appeals; for example, see how one property owner prevailed in this case study on overturning a denied tree damage claim.
When facing an improper denial, you have several powerful options:
- Formal Written Appeal: Submit the certified arborist’s biomechanical failure report along with a point-by-point rebuttal of the insurer’s denial arguments.
- Invoke the Policy Appraisal Clause: Most homeowners policies contain an appraisal clause that allows you to demand an independent appraisal panel when you and the insurer disagree on the scope of loss or causation value.
- Engage a Licensed Public Adjuster: A public adjuster works strictly for you, the policyholder. They analyze policy language, coordinate with your consulting arborist, and negotiate directly with the carrier’s adjusters to secure an equitable settlement.
- State Department of Insurance Complaints: If an insurer operates in bad faith or refuses to review objective forensic evidence, lodging a formal regulatory complaint can force a higher-level claims review.
Frequently Asked Questions About Tree Damage Claims
Can an arborist report help if the tree did not hit a structure?
Yes. If a severe storm has cracked a major trunk or partially uprooted a mature tree, leaving it hanging dangerously over your home, an arborist report can prove the tree poses an imminent structural threat. By documenting the failure of holding wood and the immediate target risk using TRAQ criteria, the report provides adjusters with the justification needed to approve emergency stabilization and removal before catastrophic collapse occurs. Additionally, for complex property line disputes where a neighbor’s hazardous tree threatens your property, a formal report serves as legal notice of negligence if the neighbor refuses to take action.
Why do insurance adjusters prefer certified arborists over general contractors?
General contractors are experts in framing, roofing, and drywall, but they lack training in tree biology, wood pathology, and tree biomechanics. An estimate from a general contractor or an uncredentialed tree trimmer only states what it costs to remove the debris. In contrast, an ISA-certified arborist provides an objective, scientific analysis explaining why the failure occurred. This directly answers the adjuster’s core questions regarding causation, foreseeability, and policy exclusions, reducing disputes and speeding up claim processing.
How long does it take to obtain an arborist report for an insurance claim?
For standard emergency storm damage assessments, a certified arborist can typically complete a site inspection and provide a formal written report within a few days to two weeks. In fast-tracked or simple residential cases, digital field capture and desktop quality assurance reviews can deliver reports in as little as 72 hours. More complex cases—such as multi-tree losses or property subsidence assessments involving root systems and soil moisture—may require extended monitoring and lab testing.
Conclusion
Navigating a major property loss after a severe storm is stressful, but you do not have to navigate the insurance claim process alone. Preserving physical evidence, understanding your policy’s coverage triggers, and securing an objective, scientifically sound arborist report are the most reliable steps you can take to protect your investment and secure a fair settlement.
Since 1991, Southern California Tree & Landscape has served homeowners, HOAs, and commercial property managers with dependable, ISA-certified expertise. Whether you need emergency storm recovery, diagnostic tree health evaluations, or comprehensive tree service, our team is here to protect your property and provide the defensible documentation your insurance claim demands.